Showing posts with label Rationality. Show all posts

Friday, August 28, 2026

Imposter

 We keep coming back from the 9th inning as Howard Marks likens it.
There are these microbreaks... like the semiconductor sell off last month.

And then the wonderkid losing his shirt because of that sell off.

What are the odd ducks right now?

1. Geopolitics - Iran, Taiwan, Russia, US, Korea, New defense alliances because of Trump's wavering mind
2. Hacking by AI
3. The massive money bubble around AI along with real capex
4. The insurance engine behind the private credit engine
5. The bond market signaling that there is no merit holding long bonds at these yields
6. Murmurs of the US losing its privileged reserve currency / treasury position
7. Inflation looks underpriced

_____________________________

On a side note a word in praise of America. 

Economy2014 GDP2025 GDPIncremental GDPShare of global increment
United States$17.6tn$30.7tn$13.1tn34.9%
China$10.7tn$19.6tn$8.9tn23.7%
ROW excluding US and China$52.1tn$67.7tn$15.6tn41.4%
World$80.4tn$118.1tn$37.7tn100.0%

Thats just the GDP.

Wait for the USD market caps:

Equity market cap20142025Increment, 2014–25Share of global increment
United States$26.3tn$68.9tn$42.6tn48.4%
China$6.0tn$15.5tn$9.5tn10.8%
ROW excluding US and China$37.3tn$73.3tn$35.9tn40.8%
World$69.6tn$157.7tn$88.1tn100.0%


This encapsulates China's lies, American chutzpah and the multiplier effect of capitalism.

(And also the upcoming drawdown)

______________________________

My plight: The imposter syndrome.

I have had reasonable success thus far but a few lessons stand out.

1. Everyone has a portfolio of which they feel confident and proud. Everyone is smart and everyone has very good tools.

So what makes me special? Am I the patsy?

2. As Pulak Prasad pointed out
There are researchers in the Arctic who have dedicated 2 generations of lives in pursuit of a single goal. And then after 60 + years, they were proven wrong.

And here we are, with our money and our chutzpah betting on businesses run by people who are actually in the know.

3. My own research of investment performance of some greats has shown poor to mediocre performance for elongated periods after having done well.

So, it reminds me of the superinvestors of graham and doddsville.

That for the longest time, there are these monkeys which survive.

And hence the monkeys start believing that they are great; until at the subsequent roll of the dice another segment of monkeys falls off.

At which point, the remaining praise themselves.

And so it goes on.

Takeaway: If I get the finish the game on my terms - that should be the goal.


4. Lastly, something I read recently on FT.

https://www.ft.com/content/7b95cdab-7546-432f-b4a1-6509e7648ec5

The purpose is to play. Come up with constraints and then play that game.

I juxtapose that onto what my friend Karthik had said:

We are lucky that we can aspire to be gentlemen of leisure.


I often remind myself;

I would like to read, learn, play to my strengths and make some money along the way.

And now another goal that is paramount: Engross myself in life with my family.


The snowball will roll as long as nuclear war is averted and I don't blow myself up.

"You dont know anything!" - My daughter sang it for me recently. 

I hope you dance https://www.youtube.com/watch?v=RV-Z1YwaOiw


Monday, June 8, 2026

We're off to see the wizard

Every bubble has its poster child.

This time, there is a lot of Gavin Baker, Altimeter Capital, Ron Baron.

And Jensen is like a superhero - going everywhere, striking deals.

I truly hope we are in a bubble that grows wild

Why? 

May you live in interesting times; as the old saying goes. (Intgly, Google AI mode corrected me saying that its not chinese by origin!)


The polarity of AI usage is amazing.

Burry, Kakashi, Ed Zitron, Databricks - they are on the other side. That the accounting, and the utility and circularity are all unsustainable or suspect.

On the other hand, with Berkshire backing Alphabet, and mega primary capital raises - along with significant cash flows going to the chip makers such as Lam, ASML, AMD, NVidia, Broadcom, and the 3 memory guys.

What we get is a concentrated new capital cycle .


And then we have the narrative of: Uber, Zepto, Airbnb, Booking.com, Gaming.

That the beneficiaries of these waves can be app developers who are solving particular problems, and ultimately, consumers. 


May you live in interesting times.


Sunday, May 10, 2026

Final days of a bubble. Or, the final 364 days.

 And just like that, we are at new global highs.


Sandisk, Samsung, SK Hynix, Micron, Intel, Kioxia and others going mad.  
Kospi is up 200% and Taiwan approx 100%

I am excited

I am scared

I am heavy

The Nasdaq is up almost 30 percentage points since the fall due to Iran was reversed.

Meanwhile, the Iran issue still remains.

The China, Japan Taiwan issue still remains.

And the US is in a recession without this AI bubble; there is a stronger divide between the AI economy and market prices, and the non AI stuff.


The battle for Investment Survival.

For a lot of oldies, they are prepared for a sharp sell off and recession, or an even wilder blow off.


Market reflexivity is at its weirdest, because we now live in a world where the oldies can warn well, the aggressive can spur on well, there are 'stages of a bubble' predictions everywhere, we are in the globally most well oiled liquid market ever; 

And as Terry Smith warned recently, ETFs and index funds have become momentum plays, and self deceit inducing plays.


I hope I survive.


Wednesday, April 1, 2026

Mandi ka moo kala

 I wonder whats up; the IEA is saying that things are going to get worse in April because physical supplies of oil and gas will actually dry up.

Helium shortage; Open AI closes a $122 B round, Pvt credit companies figuring out continuation vehicles and secondary buyers, Fannie and SpaceX IPOs?

But lets see.

The odds are that economies tend to cope.

The IVs of the OTM calls have crashed.

But one simple table shows us what can happen:


See the YoY numbers.

A country which should attract a mad amount of FDI because of AI, and where the consumption story is genuinely intact ought to rerate soon. 

In a scenario where the world goes back to normal oil and gas, or a scenario where India's heft allows it to get a chunk of the oil and gas at the expense of poorer economies, a sharp rerating is possible. 


Anyway.

Focus is always: One foot fence, low price, margin of safety, position sizing and knowing one's competence. 

I wonder if long dated calls fulfil these conditions.

Howard Marks reminded me: Best to stay in the 'I dont know' bracket of investors.


Addendum:


This is 14 days later :D
Kospi is up 185% YoY and Taiwan is up 92% YoY  


Tuesday, January 6, 2026

Remember

Remember that in 2019, even before the COVID mayhem, we had ADAG, DHFL, GMR, Yes Bank, ILFS, Crompton, Jet Airways, Essar Group, Coffee Day, Zee Group, Cox and Kings, Adhunik, Amtek, Videocon, Bhushan failing.

And since 2021 we have barely had a whimper.

No frauds, No NPAs.


Its only when the tide goes out...


Addendum:

Maduro gets kidnapped

Iran is falling? 

Greenland is being purchased?

And there is barely a whimper.

Reminds me of the Icahn interview... "I fired the whole floor, and its like a bomb went off... there were no complaints, nothing. Its like nobody even cared and nobody was ever there"

Tuesday, November 25, 2025

Complacency

 The music is playing and we ought to dance. I think this is what Howard Marks' memo is saying.

I was rewatching Margin Call yesterday: fabulous drama. 
And what struck me was the dichotomy between ex-post and ex-ante.

Back in 2006-7; the overwhelming majority was aware that 'this is too easy' and that any mention of 'risk' was rubbished away. There was genuine complacency.

Just like 1999, where anybody who got out before the bubble burst, felt left out, dumb and cheated. 

That, even in Margin Call - once the 'company' was done selling its assets, if the market recovered and continued chugging along: everyone felt like a fool.

"May be there is some oil to be found in hell".

Ex-post however, everyone sees it as alarmingly obvious; "if I was there then, I would have surely figured it out and gone into cash or sold short..."


And yet, here we are. 

Today:

"I own great companies. So what if some of them are at 40x PE"
"Well, yes. But I have 4% in cash, and look at these bargains in the other corner of the market"

As on Nov 25: Mag 7 total + Oracle + Broadcom : All 9 combined: $23.692T ( of 67.5 T US total)

As on 2019-12-31: 5,448.13 (of 33.9 T US total)


The magnitude of this is alarming. 


From the movie:

"It's just money; it's made up. Pieces of paper with pictures on it so we don't have to kill each other just to get something to eat. It's not wrong. And it's certainly no different today than it's ever been.

1637, 1797, 1819, 37, 57, 84, 1901, 07, 29, 1937, 1974, 1987—Jesus, didn't that **** me up good—92, 97, 2000 and whatever we want to call this (2008).

It's all just the same thing over and over; we can't help ourselves. And you and I can't control it, or stop it, or even slow it, or even ever-so-slightly alter it. We just react."


So, 2020 got a COVID crash; but the recovery was mad quick; there was a bit where the end of ZIRP took down a few big banks in the US, and nobody really cared. 


My point being: 

The attitude towards risk is - more is good.

There is complacency towards the downside.


Thursday, September 18, 2025

Avalanche

 A fragile system.


It looks like thats where we are.

Pvt credit using insurance subsidiaries to raise capital, and magically have no NPAs to speak of.

Cryptogeeks justifying 'underlying' whatever and using leverage from lenders who like 8-10%. Apparently there is an entire market where lending is happening to crypto stuff that is disguised as treasuries or other currencies. And this is lending is outside of the banking channels almost like the private credit mania. 

Companies getting equity capital and pre-IPO capital to keep bankrolling their acquisitions or ventures, while keeping negative ROE (something a lender would definitely not like)

The everything bubble is scary.


My wife asked me when I doubted a particular crypto: "But if its going up, and has gone up for 5 years or even 10 years, doesnt it mean that you are wrong or plain envious?"

I said: "Yes, it means that I have been wrong until now."

Akshay Khanna from Taal said it well : "Aaawaaz unchi karne se, ya chillane se, aapka jooth sachh nahi ban jaata"


But beyond whether i am right or wrong (I am right of course), the big factor is the interconnectedness of things.

The wealth effect, and the leverage effect is probably the most I have seen even if I count the IT bubble of 1990s.


I asked chatgpt this:

Here’s the “Magnificent 7” + Oracle + Broadcom market caps at 2019-12-31 vs 2025-09-17 (USD, billions). Sources are shown per row.

Company 2019-12-31 2025-09-17 (yesterday)
Apple 1,304.76     3,550.00. (StockAnalysis)
Microsoft 1,203.06     3,791.06. (StockAnalysis)
Alphabet (Google) 923.77     3,017.82. (StockAnalysis)
Amazon 916.15 2,470.21. (StockAnalysis)
NVIDIA 144.02 4,138.05. (StockAnalysis)
Meta Platforms 585.32 1,948.71. (StockAnalysis)
Tesla 75.40 1,420.00. (StockAnalysis)
Oracle 169.94 856.52. (StockAnalysis)
Broadcom 125.71 1,634.74. (StockAnalysis)

Group totals (Mag7 + Oracle + Broadcom)

  • 2019-12-31: 5,448.13

  • 2025-09-17: 22,827.11

  • Absolute change: +17,378.98

  • Multiple vs 2019: 4.19× (≈ +318.99%)

(Arithmetic shown using exact figures above.)

Notes on sources & dates

  • All figures are end-of-day market caps from StockAnalysis pages that list both historical (Dec-31-2019) and current values for Sep-17-2025; Apple and Amazon pages explicitly show “as of Sep 17, 2025.” Tesla’s page shows Sep-17-2025 in the header (“Market Cap … as of September 17, 2025”) and the 2019 figure in the history table. (StockAnalysis)


So; basically, even from pre-covid highs, we have $17 T of wealth sloshing around the world economy just from these 9 companies.


I am quite scared of a 1987 crash kind of scenario...

A fat finger, or a Meta saying that capex will drop from the guided 70 B to only 35 B would lead to quite the avalanche. 

Again - I highlight the interconnectedness risk, and the euphoric wealth effect where social media is full of people who got the right stock, and right portfolio, etc.

"We may not know where we are going, but we sure as hell ought to know where we are" - Howard Marks


Where we are is close to the summit. 

And just like the 1989 Japan, or the 1999 IT bubble, the narrative is: "dude, the world is going to change around this new epicenter, and all we have to do is sit tight."


Thursday, September 11, 2025

Fragile Markets

There is something really fragile about the top companies' makeup.

Oracle just moved to almost 1 T, Broadcom is at 1.7 T...

There are 4 big hyperscalers now; they all buy most of their stuff from 1 supplier - NVIDIA.

NVIDIA makes all of its stuff from 1 supplier - TSMC

TSMC buys most of its stuff from 1 supplier such as ASML, and the Japanese companies...

The hyperscalers are deeply entwined with particular companies.


OCI depends on OpenAI and Meta, and NVIDIA (as customers)

Azure depends on OpenAI

Google depends on itself and Anthropic

AWS has many customers?


All of them need nutty amounts of power.


If claude, or chatgpt begin losing customers (switching costs are super low now) - what happens?

__________


Then there is the pvt credit market which is also depending on steady inflows because the round robins seem to have started. Banks like JP M are simply stepping back...


___


And then, gold, bitcoin and crypto treasury companies.


____


Looks like a weird pack of cards

Tuesday, August 5, 2025

Something's off

Nov 2024: I wrote: "Boom, boom boom, and I fired those people, emptied the whole building, but not a whine... its like those people had never existed."


Somethings gotta give


And here we are in August 2025

  • The China real estate bubble burst - and nothing happened? Nobody's upset, people havent lost their life savings? Normally, when RE is a big chunk of the economy, and if RE bubbles burst, there is degrowth - how has China continued to grow?
    This makes me believe that similar to how nobody expected degrwoth and stagnation in Japan in 1985; this time too, there is degrowth and its like the 4th dimension that nobody can see.
  • Israel attacked Iran, and the nuke facilities got bombed and no retaliation?
  • Nobody cares about Gaza
  • People are bugged with Putin, but he just isnt backing down
  • Trump announces tariffs on everybody and the US economy still grows?
  • The Mag 7 turn from FCF to low FCF and yet they add trillions in market cap?
  • The Pvt Credit bubble continues unabated, and nobody cares about NPAs?
  • Crypto assets are now mainstream? I mean, it says "Crypto".
Its all very fishy.
Reminds me of when I read this book in 2015; and it took until 2022 or so for the bubble to burst.


Bad!

Sunday, November 10, 2024

Boredom

A bored mind can wander and wonder.

NVIDIA is a chip company, but does CUDA and 'locking' effects make it an OS for accelerated computing?

Also, cash spewing tech companies needed to put their cash to use; the NVIDIA GPUs is a great forced bet for so many of these companies.

Funnily, that doesnt mean its a good investment by the hyperscalers or newbies ; nor does it mean that NVIDIA cant go to $10 T from the curent $3.5 T

_______

Google had a search/ advtg monopoly; along came FB and took away a good chunk via the website facebook.com

And then, the app culture, has taken away more of Google's business.

And now, will chatgpt-esque competition change the nature of search? But does Youtube stay intact?

Also - have you noticed how whatsapp is now the primary 'mailing' app for personal, B2C and small businesses? I know people who kind of dont see their emails anymore.

______

Why did the Fed reduce the overnight rate target from 5.5% to 4.75% (4.5-4.75) in the last 60 days?

Was it an egoistic imperative to have a 'soft landing'? Because there didnt seem like any reason:

"The Federal Reserve's mandate, also known as its dual mandate, is to promote maximum employment, stable prices, and moderate long-term interest rates".

None of these seem to have been triggered.

_____

I have a folder going back to 2011 chronicling the building China bubble, and the logical fallacy of capex/ infra spending and genuine growth. I kept making new folders for every year. 

And after 10+ years of everyone praising the growth model, it looks like there were no clothes.

It's a good lesson in the gumption and humility in seeing the truth.

Similarly, what I see today is:

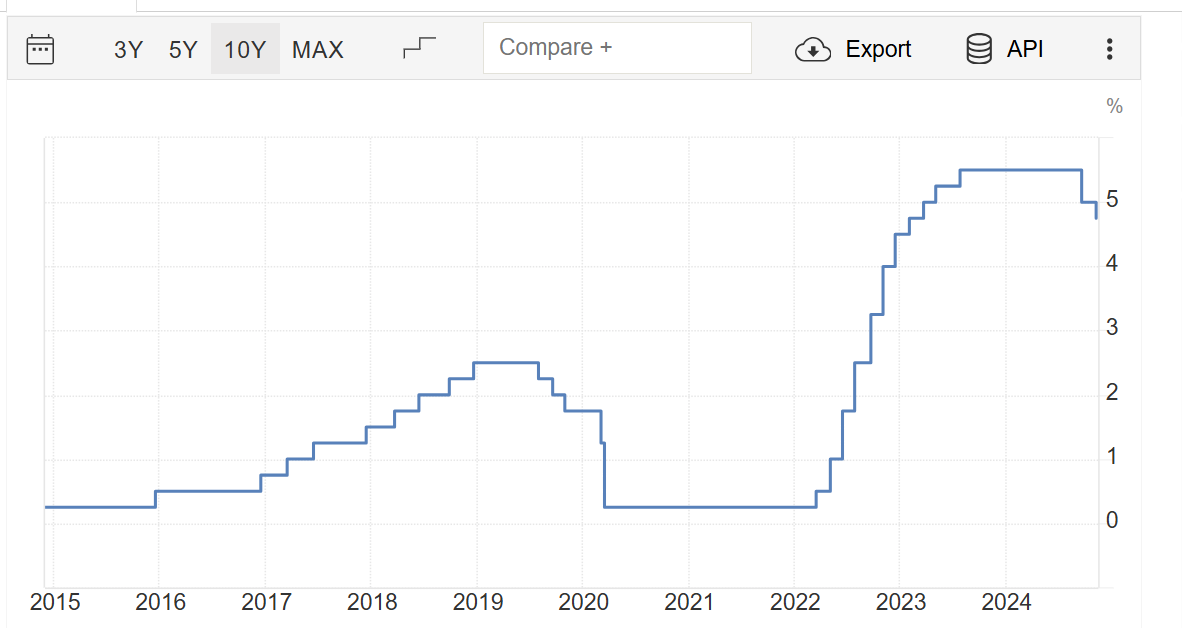
Below is the Fed Funds rate; 


And it reminds me of an Icahn anecdote: "Boom, boom boom, and I fired those people, emptied the whole building, but not a whine... its like those people had never existed."

From 2022 to 2024; nothing monumentally negative has happened; with rising rates, there were no crazy commercial defaults, gold kept going up, Bitcoin kept going up, stocks up, no spike in junk bond defaults.

It feels like China. 


And my sense is that Private funds have a lot to do with this; there is a chance that they have evergreened some assets/ loans; that the ETFization of Bitcoin has had consequences, and the underlying defaults of these private funds are hidden because of steady growth (similar to how high bank asset growth can hide default rates because of base effects)
"Private markets assets under management totaled $13.1 trillion as of June 30, 2023, and have grown nearly 20 percent per annum since 2018." 

I guess I am a skeptic at heart who believes that there is no free lunch.

And Reflexivity says that so many years of (since 2008 almost) continuous rise in asset prices has dulled rationality. 

'Stocks tend to go up', 'gold tends to go up', 'crypto is the future'. These maxims have taken a strong hold, not only in the US; but more so in Japan and India too. 

I wonder what Turkish, Sri Lankan, Chinese, South Americans, Ukrainians etc are saying to these things. 


My conclusion is: We are precariously poised. Similar to 2006-2007 where the world was oblivious to the tail of CDS and CDOs wagging the dog of the economy; and when the tail got infected, the dog could not do much... 

The music is playing and we are dancing. 


______

And dont get me started on what the political effects of a recession of world leading economy could be. One spark is all that is needed. 


Addendum: History shows that pegs dont tend to last. Wondering if there will be a cataclysmic 7.19 going to 10 someday soon. 

_______  

Boredom is a wonderful thing.  


Wednesday, August 21, 2024

Bad!

My 4 year old daughter says this: "Bad!" 

She says it for anything she doesnt like or appreciate. It could be me sitting on the sofa, me holding her right hand instead of her left, her chonda coming slightly loose, her 1 year old sister walking away... 


I say 'Bad!' to 2 things nowadays:

1. The frenzy in the market

ZIRP ended, Ukraine got attacked (and has now invaded Russian territory - :|), Gaza has been attacked, China's 12 year Real estate and GDP pumping bubble has burst, some crytos and SPACs have been declared frauds, there are zombie CRE loans in the US market, Bangladesh's PM has fled the country, US 30 yr mortgage at 6.7% v/s 8.6% floating in India

And yet, we have Bitcoin at highs, Gold at USD 2700, Nvidia at $3T, Mazgaon at 90000 Cr, Suzy at 1 L Cr, Tent at 2.5 L Cr, Tomato for 2.2 L Cr, Dixy for 75k Cr, RE projects in India getting sold out in hours and days;

Of 900 Indian companies of more than 100 Cr mcap within 10% of alltime highs , 
550 are above 30 PE, 400 above 40 PE, and 264 above 60 PE and 119 above 100 PE!

There is a flurry of IPOs, QIPs, OFS with a lot of dodgy entities buying in, a lot of big funds and promoters selling, and weird small investors getting QIPs and Pre-IPO allotments.


After 2 years of being cautious, I guess I will say it again: Somebody's gonna get a hurt real bad.

And this time, it looks like a lot of retail investors have already gotten clobbered in the F&O mania, but many are still holding onto 120 PE good companies, and 30 PE rubbish companies... I see a lot of companies falling 80-100 %.

Of course, my portfolio is pristine!


2. We are forever elsewhere.

An episode in Seinfeld, where Elaine goes to a store to rent a video cassette of a movie recommended by ' Vincent '. She plans a trip to the store, browses through the wares, speaks to a friend, rents a cassette and puts it in her bag. At the end of the day, she plans to curl up in bed, and watch the movie - not knowing if it is bad or good - and surprise, its a good movie! The only disturbance through the movie was a phone call on a landline - she picks up the call and it is always a surprise as to who the mystery caller might be.

The paradox of choice and leisure means that we are often at rest - so, browsing in a store is no more leisurely than munching on chips at our bigger homes with big TVs and a choice of 500 movies and 200 TV shows to choose from. We know what we want to watch, because we already know the good reviews from the bad. 

We are not disappointed anymore... We know the best dish from the best restaurant comes to us within 30 minutes. If you want a coca cola, it is at your doorstep in 9 minutes flat. 

We can send a toothy guffaw smiley to a friend on whatsapp to convey that we are smiling even though we might not want to really meet this person.

When was the last time that someone was surprised to see you? Or you were surprised to hear from a friend? Or you pick up a book and oh! it turns out to be amazing! 

And all of the above is without mentioning the horror that is social media. 

Why am I looking at a 25 second video of 2 random people dancing? Am I not supposed to hold my baby by her arms? Microplastics in my salt? They/ Them - who is this person who is offended in a small town in the US... wait, do I care? Oh, so this is how my glutes are supposed to look...


Bad!

We were looking for leisure, comfort and entertainment.

We got it - and with that we got poor mental health, attention deficit, restlessness and dissatisfaction (because this was rated 97% on Rotten Tomatoes but it wasnt that good), alone-ness, distance from real connections and real conversations.

So, did we win?

Bad!!

Sunday, May 21, 2023

Goals

My best old investment seems to have done 16% compounding for 10 years and it remains terribly undervalued. It was a sizeable investment and hence, the metric matters. 

Smaller investments have done better and worse than this.

 And yet, where I stand now is on the shoulders of all those losers and winners and not just this one investment.

 My current learnings are taking me to an appreciation for businesses that dont need incremental capital as they grow; and I know now that there are all kinds of creatures that win at the game...

One of my more recent investments (and the result is shocking as I have just calculated it in this last minute) has done north of 40% compounding in the last 5 years; and this too seems undervalued to me. But more scarily, it looks peak-ily poised because that might be the nature of the business.

Of course, I leave out the 100% and 97% drops I have had in the past, and the 8 year 2x I have had... which have brought me to a respectable rate of wealth growth.


But these musings get me back to why I am playing this game...

Independence has been achieved. The safety cushion has been established. But the way here is the way forward; to feel the stones and keep walking along.

I need to remind myself that I'm here not to win.

I am here to play, and I will play this game on my terms. 

That, oddly, even a 10% CAGR is enough :|

That I better learn from the muddy puddles and broken stones from the past.

That my ego wants me to win, while my system 2 wants me to have fun.

And the risks I am cognisant of are those of health, family, politics, luck, society, war and natural disasters.

It's my fortune that I have to worry about little else.

Monday, November 28, 2022

Are things changing?

Things dont tend to change. People like sweet things, people like carbohydrates, people need materials like cement, steel, plastics, people like brands, people struggle for power and prestige and incentives tend to be strong influencers.

What are the changes I am seeing?

  • Modes of transport
  • Need to save the 'climate' vs the economic hardships of doing so
  • Global engines of manufacturing
  • Budget/ Economic deficits in the large economies

Modes of Transport

People dont need to commute as much - their entertainment can be at home and their work can be done from home.
When traveling, electricity seems to be powering more vehicles. Whether it will be hydrogen, LFP, aluminum; I dont know. But it seems fairly clear that oil based vehicles are going to decline substantially.

-   What these things do for oil, refining, mining, manufacturing, plastics, downstream industries, OPEC, Australia, Congo, etc - are quite uncertain. 

- What the advent of oil did for a lot of OPEC countries was unprecedented; but 100 years ago, nobody would have bet on UAE or Saudi' prosperity; and similarly, one would have thought Venezuela to be unimaginably rich


Climate

Life seems to be struggling against climate change - some life will thrive and others wont. The culprit seems to be too many humans caring single mindedly about convenience and economics.

Now, does that make the US a safe haven against climate change vs a Europe that's getting colder or coastal megapolises that might drown or get damaged? Could a mega-cyclone change the way Indians behave? Will there be a tipping point that leads to a mass movement of people away from certain countries?
Could there be a famine in a developing nation? 

And how should a family protect itself against something like that? 


Manufacturing

Apparently, its mad difficult to set up a new manufacturing facility in parts of Europe. Either its the people, or the local laws or the green police that makes things difficult. 

China seems to have been uneconomic in its manufacturing decisions over the last 10-15 years; will there be a resurgence? Doubt it. But will the South and South East Asia be the new manufacturers for the world? Seems quite likely - with the abundance of people, along with people with brains and people with capital to power it. 

Could this be the next 20 years of a non-China manufacturing powerhouse?


Budget/ Economic deficits in the large economies

I have often looked with disdain at poor European countries with people living cushy lives - I just cant figure out how they can afford it. As is said; there is no free lunch.

The US too seems to have a big crisis that has been in the making for the last 30 years or so - the Medicare, Medicaid, Pension, old people problem.

How do these things influence policymakers or central bankers? 

Canada, NZ, Australia seem to have realized that they need immigrants to power their economies - physically and economically. Will the US and Europe really awaken to that? 

Could we be facing a 20 year period of austerity?


All these are just musings. They are fun to ponder over but they dont seem to influence my big investment decisions.

But yes, they are influencing my backup/ insurance policies. 

I am trying to get ready for the 'what if?' scenarios.


Monday, July 12, 2021

Irrelevance

I have often found solace in physics. 

Is it the observer that exists, or is it the observed?

How big is the earth relative to the time/size of the universe? 

And how tiny can things get?

And in that mix, we have us - trying to watch random price movements of a few securities of a few companies which are mythical beings which provide 'stuff' to customers and make some mythical money , which we believe belongs to us.

And all this while we are busy decaying and going back into the universe, and our minds can only fathom these smallest of time increments and futures and pasts; our brains plague us with thoughts and visions of things which are not there and futures which may never happen and emotions which were never emoted.

When we say that it is our duty to 'do', I believe we are just 'going along with it...'; but what choice do we have? Except for the end game, there is no other way but to 'do'.

And this deed is what we have the option of choosing, along with how to fulfill it.

And so I say, that investing is a means of entertainment and enrichment - and in that lies my north star. If I could shed my greed and envy and fear, I might just enjoy all this a lot more.

A few more decades to go - hope I play towards it.


Meanwhile, the everything bubble is real. And we just keep dancing along.

The coin mania, SPAC mania, EV and tech and 'no capital' mania will fade - history has proven it. 

But this should be very interesting indeed. 

Lets see how these Indian companies fare.


Notes: RE, Chemicals, Financials and Indian consumption.


Monday, May 4, 2020

Independent Thought

"It's not supposed to be easy; anyone who thinks it's easy, is stupid."
This confused me; yes, it was hilarious, but I couldn't figure out why it was funny.
In the middle of this COVID pandemic crisis, I really get it.
In fact, I have been 'getting it' for the last 2 years where drawdown after drawdown faced me in my investment portfolio.

And yet, I can humbly say that value investing works. Buying with a margin of safety works. And as my friend AR reminds me, (the same as I remind some of my people), the journey is supposed to be fun; and I must say that the fun is back.

In 2008-9 when the great recession struck, I was still in India, but I began reading about financial stuff, and one of the things that hit me was that the US GDP was $14T in 2010 or so.
As I write this, they are pushing $21T.

What I have often seen now is that people misunderstand GDP as a stock number, but is in fact a flow number; that country's revenue line is $21T or so; in the meanwhile, India went from $1T to almost $2.7T now - which is fabulous when it's measured in % change, but while the US increased its yearly output/ consumption by $7T; we managed to increase the annual output by $1.7T.

The way all this has influenced me has been:
I would like a substantial portion of my wealth to emanate from countries where capitalism is important, to where the best minds of the world are attracted and where the rule of law and recourse can be counted upon.

As I look back at these past years investing in India, I have seen the retrospective taxation by the GOI, I have seen a mass cancellation of mining and telecom licenses, an overnight eradication of hard currency from the system, a closet full of skeletons tumbling out (be it over-indebted loss making PSUs, fancy and sometimes trusted business names, companies with connections with the underworld, prominent business folk running away from India), a Chief minister of a state unilaterally cancelling a bunch of projects/ contracts that his predecessor entered into, and behind which those companies invested substantial amounts of money, a non-existent telecom player surreptitiously buying a pan-India telecom license from another company which is essentially bankrupt now - meanwhile, said telecom company is now the biggest in India and nobody mentions how it got a pan-India license, a complete and total illiquidity in the wholesale financing market for non-banks, a humungous backlog of bad loans by the public and private sector banks (which includes many cases of blatant fraud and complete oversight in other cases).

Many folk in the business circles call this a 'trial by fire'; a change in the way India will operate, where there is a fear of the law, where a businessman cant keep looting public money, where politicians are accountable, where the mythical magical Indian middle class will finally emerge, and how the companies that survive will reap and spread these benefits to the population.

The beauty of capitalism is that some companies adapt and continue chugging along, they manage to change with the times - by enabling a certain culture, or by borrowing cheap in the overseas markets, or by diversifying their field of operations, or by narrowing their focus on the things that matter - all the while figuring out how important people and balance sheets are.

COVID
The more things change, they more they remain the same.
There is a flurry of activity in webinars, politicos, news and the like about how life is going to change, about how there is a growing resentment towards China, how global supply chains will change, how a lot of these first world countries will make contingency plans to deal with such a pandemic again - and I believe that while things will change, the forces of the free market are so strong that it will be difficult for a country to begin erecting trade borders with tariffs/ embargoes.

Eventually, money flows to some of the best companies in their geographies/ fields; while this may be the new gold rush towards specialty chemical companies in India or SE Asia, only the better companies will thrive as has always been the case when market dislocations reach equilibrium.

What could be?
I wonder - is it high time that the Eurozone breaks up? I believe it has gone on for far too long. How can Portugal continue caring for Greece continue caring for Germany and so on?
How could it be that the US has the ability to pay 1% p.a. for 10 year money?  That said, how did Japan do it for all these decades?
As LL predicts, will China finally move towards a free-r market system where the government only plays the role of peace-keeper and co-ordinator? Could the RMB become a major international currency? May be the route to that will be after a strong devaluation in the RMB...


My life
While the country around me is struggling with making ends meet, or trying to get back home, where 70% of rural India does not have access to running water (and the WHO can keep shouting 'please wash your hands) I am sitting in a privileged position where I am reaping the benefits of the work done by my ancestors.
What is my dharma towards the world?
There is a new being entering my life in 2-3 months, how will that bugger change me?
And how does all this tie-in with my investing style?

Lessons:
A more diversified portfolio.
A more stringent quality check on promoter quality.
Knowledge that more things can happen than will - the next crisis will be really different; it might actually be a crazy bubble in gold?
The relation between price and value is still sacrosanct; but the thing I need to learn is change in value over time and how Mrs. Market perceives companies where value is changing.

Do I own too many companies today?
Am I too lenient towards my smaller holdings, and I just let them run...?
Will Real Estate offer me the rewards I can imagine today?

Or - is the primary lesson that I cannot allow my sleep to be hindered, while I had this condition earlier too; I guess I was too naive. As is said, I should be able to learn by the time I get through the first 30 years or so.

My companies
Cheap, ready/ readying for the future, becoming stronger, have proven to be good at their work and will soon face new crises of their own.
Auto, Finance, Wealth, Chemicals, Consumer Brands, Real Estate, Pharmaceuticals - but the string running through them is: cheap, good runway, good balance sheets, global operations and yet - not very high on ROC.
Is this a big mistake? Or is it my inability to pay up? Or is it my inability to connect high ROC and low growth?

A thought that has stuck with me is: " My portfolio is the best." What this means is that each investor or fund manager surely believes that his or her portfolio composition is the best that could be done; and interestingly, the permutations that it throws up for the number of companies that are deemed investment-worthy is extremely high.
All of which implies that we can only do a certain amount of justice with the cards we have been dealt.
The smartest and most hard working or most experienced investors can still say that they have looked under far more rocks than the newbies, but there is simply a lack of time or initiative or luck with most of us.

And all this leads me to the superinvestors of Graham and doddsville. This is THE document which got me here and where WB postulated that all his fellow monkeys had their own set of companies and varying styles of investing but the central tenet was that things need to be bought with a margin of safety and that price is what you pay and value is what you get.

So, this is where I stand.
We are surely on the cusp of the next round of 10x and 100x in this country.
We are also relatively lucky that while the world is being extremely carefree about the perils of modern monetary theory, we have thus far reined in our looseness. 

While there are clouds of a strong devaluation of the rmb, or a break up of the euro zone or extremely high inflation or stagflation in the US, I can see that the Indian economic engine can surely find a way of finding niches and chugging along.

We are still on the ground floor when it comes to per capita wealth, and we still live in the country where the urge to pee in peace is greater than the urge to pray.


Dharma
To have fun while attempting to increase knowledge and wealth.
I am sure I'm going to do well, but as CM says, envy is the deadliest sin.
This COVID mania ought to pass.
We will soon have a bigger problem on our hands...

Wednesday, May 15, 2019

Doubt

I am throwing in the towel now. Have had enough. Nothing seems to work.
Reminds me of the Zombieland quote: " I avoided people like they were zombies before they were all zombies. Now that they're all zombies, I kinda miss people."
I miss the good old days when India was a great success story, and companies were strongly geared for growth - wait, was that just 1 year ago?

This is the despair phase of the market. The same market that I entered in 2013 when the older investors were tired. The cast is different but the eternal truth remains.

If I buy (hang on to) good companies at cheap valuations that earn decent returns on capital, and are good to weather most kinds of storms; I ought to do well.
- Now that was a mouthful and also, a mindful.

Mrs. Market is depressive. And there are decent pockets of pessimistic valuations - I am saying sub 7 PE types.  

But now I ask, 'How do I escape my old ideas?' 'Am I stuck with older companies because I believe in their value?' 'Have I become complacent in my assessment of newer companies?'
'Am I reading enough?'


Doubt - I think it makes for a good future.The stress that I had been under was worth my time; and somehow there is a certain peace now that my losses seem to have crystallized.
Somehow I am accepting my fallibility.

Saturday, October 6, 2018

There and back again

Was I Buff T. Warren?
I dont think so; although the lure of 'great quality companies tend to do well' had been extrapolated far.
I remember my pangs of 'I missed it!'

Klarman was right in 1999 when he asked whether Buff T. Warren's portfolio looks an awful lot like Warren Buffett's... The lure of good quality companies got to WB too.
And if WB can go through it - well, we are but mere insects.


I remember thinking -
no damned Mutual fund owns Y company,
there is no decent report out about J company,
investors dont even know what C company really does,
investors thoroughly doubt W company's ability to grow without losses;
And hence, I believed that I am alright.

So in the end, I have to believe that Mrs. Market is simply depressive.
And as is often believed about depression - no bother! just go for a nice comedy and things will be fine - Mrs. Market's depression has no firm rationale.
As I often tell my wife - 'When you gotta go, you gotta go!' - and then she complains about me being in there for an hour.


I was ready for this I believe. (And yet I was fully invested!)
I started making a folder called 'DONT PANIC' (inspired by Hitchhiker's Guide to the Galaxy) in Aug 2016 when too much money was made too fast.
I have not needed that folder until this week.

And the last 2 weeks' events reminded me of something Arpit had may be said: "All money made in the stock market is only a short term loan ready to be called back".

CM has often said "If you are not ready to take a 50% drawdown, you should not be investing"

Now, as Howard Marks often says: We may not know where we are going, but it's very important to know where we are. I guess he meant it about the investing philosophy.

Where are we now?
- In a country that adds may be 13m + net people a year
- Where people still have to buy their first homes
- Full of extremely young people which may cause odd social problems
- But somehow, everybody is getting access to the internet
- Very high savings rate in the country
- A very good ecosystem to service the world (mfcg and services)
- A nominal GDP growth rate of 11-12%+
- A formalisation of people's way of living - identity, credit, electricity, etc
- An irritable world leader who should be thrown out 6 years from now for sure.
- Overcapacity and bubble in the 2nd largest economy in the world
- Slightly higher oil prices
- A more competitive rupee that harms our import bill but makes our export bill awesome


"Risk for them is not being stupid but looking stupid."
I look stupid right now.
But this seems like the point of least risk.
Seems.


Friday, September 21, 2018

Biased about Biases

There are too many biases.
Actively managing the portfolio is a bias; and being too passive is a bias.
A Concentrated portfolio is a bias to conform to Munger's thoughts and a diversified portfolio is a bias to dissipate risk.
Managing other people's money causes incentive and agency biases, and managing only your family's money makes you complacent.

There are lures of greed and envy and exciting names and fantastic prospects,
As Marathe's post said: Biases about circle of competence can interfere with pursuit of knowledge - - many sectors tend to fall outside a value investor's realm of understanding; and yet, a pharma company or a commodities oriented company or a telecom company are still businesses - and these have generated wealth over decades - so, is it our complacency, or is it our bias that keeps us in the consumer goods/ financials spaces?

As my friend Arpit said, there are no fixed ways, and we have to find our way with our investing styles. And once we find that style, may be the style can change, there are no set templates.

So, what should a value investor do?

If the basic principle is margin of safety, then one should keep reverting to that.
And then, one can pursue a pharma company or a graphite electrodes manufacturer, or a lender, etc.
The balance between price and value, and an operator's ability to be an outlier in his industry, can be maintained.
The balance between a megacap and a small cap can also be maintained. A 100 Cr mcap company may struggle to grow because it doesnt understand the power of IT or employee empowerment, and a 50000 Cr mcap company can grow because it has the world as its addressable market; while we still believe that small caps tend to give better returns than large caps.

I last wrote in April 2017; and since then it seems that India has become stronger, companies have started investing again, we have seen a mad rally in the stock market and a great corrective phase now.
But how are our companies?
There seems to be a big dichotomy in lenders (v strong and v weak), there seems to be an unforeseen impact of China environmental/ economic clampdowns on Indian chemical complexes and paper and recycling, and commodities, Indians seem to be becoming much more mobile - for work and leisure.
Things seem quite good.

As for my favourite bias - I remember Mr. Bean's host in the US in the movie.
Mr. Bean was entrusted with taking care of a valuable painting - Whistler's mother.
And he told Bean: "Do nothing! And nothing will go wrong!"
Of course, soon after, Bean was drawing over the painting with a sketchpen.

So, I remind myself; as long as my companies are good:
"Do nothing! And nothing will go wrong!"
Of course, I could get hit by a cab, but that's another story.


Monday, April 24, 2017

What would an alien say

Some years ago, I wrote that if an alien were to visit Earth - and that sets the stage for how we should see things - they would say that English was invented in the US.

And now it occurred to me that if they were told that there was a global financial crisis in 2008-9, they would say - - ah, it started in Europe and Japan. No wonder they are doing so poorly.
That's quite something - somehow the originator of the crisis is faring rather well right now, and geniuses, and capital following them are still flocking to the US.

What would they say about India?
- may be, why are people leading such sorry lives, especially in very some sorry state of being.

An alien was at Sanjay Bakshi's seminar a few days ago, and she told me that - this is a very large number of people who seemingly dont want to find the next best investment idea... but want to learn about psychology and human fallacies. Pissed off biases and such.


Friday, April 7, 2017

Seeing the forest

As I try to make sense of why my portfolio has done so well, I realise that my concentrated portfolio has done well because of luck, and a very strong tide.

It's easy to say that my chosen X company has done well, performed well, and is building a foundation for future growth; but when I see the forest, I notice (almost all of a sudden and rather scarily) that too many companies have grown manifold.

It reminds me of the 2010-2012 time frame when people looked back at the 2004-2008 boom and said that you could throw darts to choose your companies and you would have doubled and tripled your money in quite a few names.
Pharma, housing finance, finance, textiles, chemicals, consumer products (but not FMCG), some auto, agrochemicals - a ridiculously large number of companies have been priced very strongly - and at times those prices seem to reflect true value, and in other cases they have gone way beyond their optimistic values.


And yet, infrastructure, telecom, hospitality, some auto, public sector banks, have performed rather poorly - - here, the prices seem to reflect the capital destroying capabilities of these companies.


The question is: Will today be a day when I will look back and say - man, this was never sustainable, and I was being too rosy about my own companies and it was all luck
Or
yeah, sure, there was a big correction but quite a few companies became stronger through the ensuing period even though I was lucky to have made returns up until this period.


The tide is bound to go out.
I have to focus on keeping my focus on the facts.
Support Wikipedia